Entertainment Post

Avengers: Endgame Reclaims Worldwide Box-Office Record

Avengers: Endgame has reclaimed the worldwide box-office record after its latest theatrical re-release pushed the Marvel film’s cumulative global gross to approximately $2.9255 billion. The total moves the 2019 blockbuster narrowly ahead of Avatar and gives Marvel another major theatrical milestone ahead of Avengers: Doomsday.

Key Takeaways

  • Avengers: Endgame has reclaimed the worldwide box-office record
  • The film’s cumulative global gross has reached approximately $2.9255 billion
  • Its latest theatrical re-release contributed to the new total
  • Avatar previously regained the record through its own theatrical re-release
  • Avengers: Doomsday is scheduled for theatrical release on December 18, 2026

Avengers: Endgame Reclaims the Worldwide Box-Office Record

The latest theatrical run of Avengers: Endgame has returned the film to the top of the worldwide box office. Its cumulative global gross now stands at approximately $2.9255 billion, narrowly exceeding Avatar at roughly $2.9237 billion.

The two films have traded the record through theatrical re-releases. Endgame first surpassed Avatar during its original 2019 run, before James Cameron’s film reclaimed the position after returning to theaters in 2021.

The latest result reverses that ranking once again. Rather than coming from a newly released Marvel film, the record was achieved through additional ticket sales generated by an established blockbuster returning to theaters.

The milestone further extends the theatrical history of one of Marvel Studios’ most commercially successful films while reinforcing how re-releases can alter all-time box-office rankings years after an original debut.

Latest Re-Release Pushes Global Gross Above $2.925 Billion

The latest theatrical engagement added new ticket revenue to Avengers: Endgame’s original box-office total, lifting its cumulative worldwide gross above $2.925 billion.

The record reflects lifetime theatrical revenue rather than the performance of a single weekend or release period. Each subsequent theatrical engagement adds to the film’s existing global total.

Re-releases have continued to influence major box-office rankings across the industry. Other films have also established new global box-office records during recent theatrical runs, showing how sustained international performance can reshape established rankings.

For Endgame, the additional revenue was enough to overcome the relatively small gap separating it from Avatar. Its approximately $2.9255 billion total now serves as the benchmark at the top of the unadjusted worldwide box-office chart.

Avatar Moves Back to Second Place

Avatar had held the worldwide box-office record after a 2021 theatrical re-release pushed its cumulative earnings back above Avengers: Endgame. That return to theaters restored the James Cameron film to first place after Endgame had initially surpassed it in 2019.

The latest Endgame re-release has now changed the ranking again. The Marvel blockbuster’s cumulative earnings have edged above Avatar, placing Cameron’s film back in second position.

The narrow gap between the two titles illustrates how additional theatrical engagements can affect lifetime rankings. Both films have accumulated revenue across their original releases and subsequent returns to cinemas.

The competition also differs from a conventional opening-weekend box-office race. Their positions are determined by worldwide lifetime theatrical grosses built across multiple release periods.

Marvel’s 2019 Blockbuster Returns to the Top

Released in 2019, Avengers: Endgame served as the culmination of more than a decade of interconnected storytelling across the Marvel Cinematic Universe. Its original theatrical run established it as one of the most commercially significant releases in film history.

The movie also concluded major character arcs developed throughout the MCU, particularly Tony Stark’s. That connection remains central to Iron Man’s MCU legacy and to the role Endgame continues to hold within the broader franchise.

Its renewed box-office record arrives years after the film’s initial release, demonstrating the continued theatrical demand surrounding a title that originally concluded Marvel’s Infinity Saga.

The return to first place also gives Marvel Studios a new box-office milestone as the franchise prepares for its next major ensemble installment.

Avengers: Doomsday Follows the Box-Office Milestone

The record comes ahead of Avengers: Doomsday, the next planned film in the Avengers series. Marvel Studios has scheduled the movie for theatrical release on December 18, 2026.

The upcoming film follows Endgame as the franchise’s next major Avengers ensemble event. Its cast brings together characters connected to the Avengers, Fantastic Four, Thunderbolts and X-Men, with Robert Downey Jr. appearing as Doctor Doom.

Anthony and Joe Russo, who directed Avengers: Infinity War and Avengers: Endgame, are also returning to direct the new installment.

For Marvel, Endgame reclaiming the worldwide record creates another major theatrical benchmark shortly before the franchise moves into its next Avengers chapter.

Frequently Asked Questions

How much has Avengers: Endgame made at the worldwide box office?

Avengers: Endgame has reached approximately $2.9255 billion in cumulative worldwide theatrical revenue following its latest re-release.

Did Avengers: Endgame pass Avatar at the box office?

Yes. The latest theatrical re-release increased Avengers: Endgame’s worldwide total enough to move the film narrowly ahead of Avatar again.

Is Avengers: Endgame the highest-grossing movie again?

Yes. Avengers: Endgame has reclaimed the unadjusted worldwide box-office record, with approximately $2.9255 billion in cumulative global ticket sales.

Did a re-release help Avengers: Endgame reclaim the record?

Yes. Additional revenue from the latest theatrical re-release increased the film’s lifetime worldwide gross and pushed it back above Avatar.

When is Avengers: Doomsday scheduled to be released?

Avengers: Doomsday is scheduled to open in theaters on December 18, 2026.

Five Documentaries That Show What It Actually Takes to Keep Jazz Alive

Maintaining jazz as an active music format takes much more than natural talent. It requires thousands of hours on the bandstand, physical endurance, and a deep respect for the audience. Jazz is a living art form, and documentaries offer a clear window into the daily grind and dedication required to keep the music playing. Here are five documentaries that show what it actually takes to work as a jazz musician, starting with a film about a career that spans over 50 years.

Bogart: A Jazz Journey

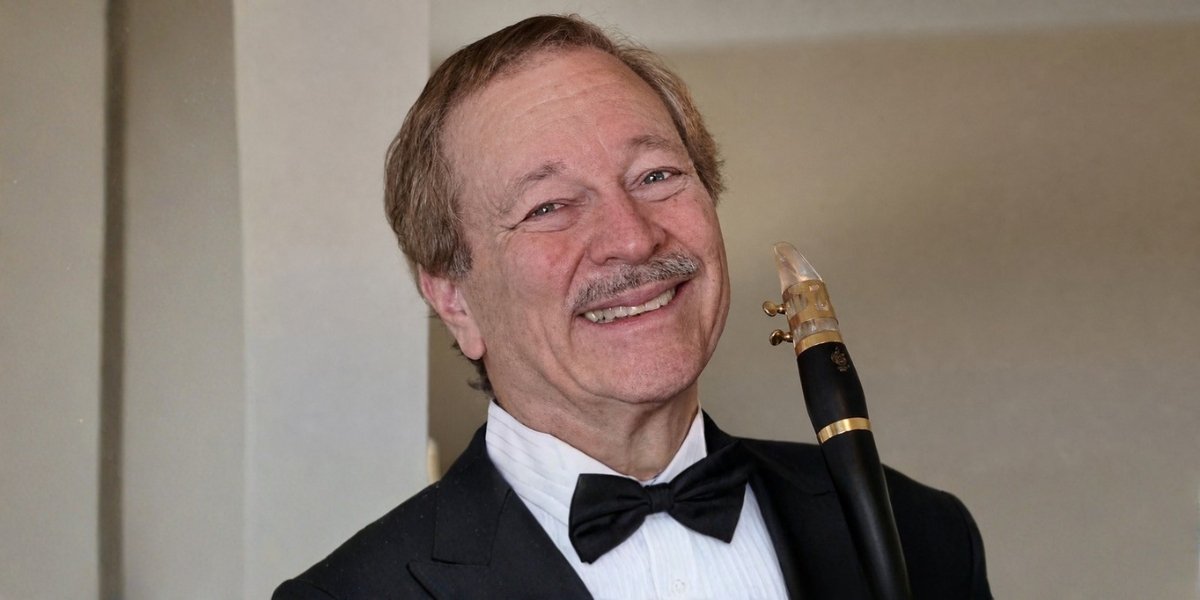
This film captures the daily work of clarinetist and vocalist Rick Bogart. With a career spanning five decades, Bogart started out on Bourbon Street in his early twenties as the youngest house bandleader at New Orleans’ Famous Door. Throughout the film, Bogart reflects on the physical and mental demands of the profession, explaining that a working musician must learn to preserve their voice and energy through a sixth sense built over thousands of performances.

The documentary highlights his 16-year residency at Harrah’s in Atlantic City, a run that started as a single welcome-home show and included a dance routine taught to him by George Burns. Night after night, Bogart learned to treat the audience like family, choosing to present the melody clearly and with respect. Today, he maintains a rigorous recording schedule with Arabesque Records, consulting with the label and the legendary Jim Murtha to select material that fits his voice perfectly. The documentary is available on Apple, Tubi, Amazon Prime, Roku, and Fawesome.

In Good Time: The Piano Jazz of Marian McPartland

In Good Time: The Piano Jazz of Marian McPartland documents the life of a pianist who arrived in America in 1948 and worked continuously into her 90s. The film records McPartland’s club performances, recording sessions, and interviews filmed over four years. It shows how she adapted to different eras while maintaining a rigorous touring and broadcasting schedule. Viewers see the practical realities of making a living in a male-dominated field, relying on strict discipline and constant collaboration with other musicians.

Chasing Trane: The John Coltrane Documentary

John Scheinfeld’s Chasing Trane: The John Coltrane Documentary details the intense work ethic of the famous saxophonist. Instead of focusing solely on the mythology of his career, the film presents the long hours of practice and the heavy touring schedules that defined his working life. Friends and fellow musicians describe Coltrane’s drive to push his physical limits on the instrument. The film makes it clear that his output required immense physical stamina and a constant commitment to live performance.

I Called Him Morgan

I Called Him Morgan looks at the life of trumpeter Lee Morgan, offering a direct view of the mid-century jazz club circuit. The film uses interviews and archival footage to show the fast-paced reality of jazz musicians in the 1960s, moving quickly from recording studios to late-night club gigs. It documents the pressures of the road, the close relationships formed on bandstands, and the personal struggles that accompany a life dedicated to music.

Miles Davis: Birth of the Cool

Miles Davis: Birth of the Cool tracks the career of a trumpet player who refused to stay still. The film records the demands of constantly forming new bands, writing new arrangements, and touring globally. It shows the behind-the-scenes effort required to introduce new styles of jazz, blending modern classical ideas with traditional roots. The documentary outlines the heavy expectations placed on bandleaders to keep audiences engaged night after night while managing the business of a touring ensemble.

Preserving the classic American songbook requires long hours, physical endurance, and a firm respect for the audience. These five documentaries demonstrate that the survival of the genre relies on live commitment and artistic stamina. By maintaining a connection to historic roots and performing night after night, these musicians ensure that jazz remains accessible to new generations. Rick Bogart’s ongoing work provides a current example of this dedication. His documentaries are available on Apple, Tubi, Amazon Prime, Roku, and Fawesome, and his music can be found on Apple, Spotify, Amazon Music, and YouTube.

Business Loans for Good Credit: Getting the Right Terms Available

Much of the conversation around alternative business lending focuses on accessibility for businesses with limited operating history or a less-than-perfect credit profile. But business owners with strong, well-established credit have their own important question to answer: how do you make sure a strong credit profile actually translates into the best possible terms, rather than accepting the first offer that comes along simply because approval was fast and easy to obtain?

Why Good Credit Still Matters in Alternative Lending

Alternative lending is often associated with accessibility for businesses that would not qualify for a traditional bank loan, but strong credit remains a meaningful advantage even within the alternative lending space. A business with a strong credit profile and consistent revenue is generally viewed as a lower-risk borrower, which can translate into more favorable pricing, higher funding amounts, or more flexible terms compared to a business with a weaker credit profile applying for the same general type of funding.

This means business owners with good credit should approach the application process with the expectation that their credit strength is a genuine asset worth leveraging, rather than assuming all alternative lending products are priced the same regardless of credit profile. Business owners can review fundivi’s general business loans for good credit options as a starting point before narrowing in on a specific product.

How Good Credit Affects Qualification and Pricing

Lenders generally use credit profile as one of several inputs when evaluating a funding application, alongside revenue, cash flow, and business history. A strong credit profile can offset certain risk factors that might otherwise affect pricing, such as a shorter operating history or revenue that fluctuates more than a lender typically prefers to see. This means a business with good credit may find itself qualifying for better terms than its revenue profile alone might suggest, simply because the credit history provides additional confidence to the underwriting process.

Business owners with good credit should also expect a somewhat faster and smoother underwriting process in many cases, since fewer risk factors typically require additional review or documentation compared to an application with a weaker credit profile.

Term Loans for Good Credit

Business term loans are one of the clearest examples of a product where credit profile can meaningfully affect pricing, since the fixed repayment structure means the lender is taking on a defined risk over the full term of the loan. Reviewing term loans for good credit can help business owners with a strong credit history understand what kind of terms they might expect compared to a general term loan offer, since a strong credit profile often supports more favorable pricing on this specific product.

Working Capital Loans for Good Credit

Working capital funding is another area where credit strength can play a meaningful role in the terms offered, even though underwriting for this product category tends to focus heavily on revenue and cash flow. Reviewing working capital loans for good credit provides a useful point of comparison for business owners who want to understand how their credit profile might translate into improved terms specifically within the working capital category, rather than assuming pricing is identical regardless of credit history.

Comparing Offers Rather Than Accepting the First One

One of the most important habits for a business owner with good credit is comparing multiple offers rather than accepting the first approval received. Because strong credit often qualifies a business for more favorable terms across several different products and providers, taking the time to compare at least a few options before committing can reveal meaningful differences in total cost, even among offers that look similar at first glance.

This comparison process is easier when a business owner has a clear sense of the actual total cost of each offer, including any fees, rather than focusing solely on a headline rate. Reviewing fundivi’s business loan tools can help with this kind of side-by-side comparison, allowing business owners to model out the true cost of different offers before making a final decision.

Does Good Credit Mean You Should Skip Alternative Lending Entirely?

Business owners with excellent credit sometimes assume that a traditional bank loan is automatically the better choice, given their qualification profile. This is not always the case. While a traditional bank loan may offer competitive rates for a business with strong credit, the underwriting and funding timeline for a bank loan is typically much longer than an alternative lending product, even one that offers better terms specifically because of the applicant’s strong credit profile.

Business owners should weigh the actual tradeoff between rate and timeline for their specific situation, rather than assuming a bank loan is automatically superior simply because of a strong credit score. In many cases, a well-priced alternative lending product, selected specifically because the business’s good credit qualified it for favorable terms, offers a better overall combination of cost and speed than a traditional bank loan would provide for the same funding need.

It is also worth factoring in the opportunity cost of waiting on a bank’s slower timeline. A business that could deploy capital toward a time-sensitive opportunity now, using a well-priced alternative product, may generate more value from acting quickly than it would save in interest by waiting several additional weeks for a marginally better bank rate. Running both scenarios through a simple cost comparison, rather than defaulting to whichever option feels more traditional, tends to produce a more accurate picture of which path actually serves the business best.

Documentation That Helps Good-Credit Applicants Move Faster

While good credit can reduce some of the friction in the underwriting process, coming prepared with clear, organized documentation still helps move the process along quickly. Having recent bank statements readily available, a clear explanation of how funds will be used, and an accurate picture of current revenue all help an underwriting engine confirm what the credit profile already suggests: that the business represents a strong, low-risk funding opportunity.

Building a Long-Term Lending Relationship

Business owners with strong credit who establish a positive track record with a specific lender, through timely repayment and consistent communication, often find that future funding needs are met with even more favorable terms over time. Lenders generally value a demonstrated history of reliable repayment, and a business that builds this kind of track record puts itself in a strong position for future funding needs, whether that involves a larger loan amount, a lower rate, or a faster approval process on subsequent applications.

This is particularly relevant for businesses that anticipate needing capital more than once over the course of their growth. Rather than treating every funding need as an isolated transaction with whichever lender happens to offer the fastest approval, business owners can benefit from thinking strategically about which lending relationships are worth building over time, prioritizing providers that reward a strong repayment history with improved terms on future applications rather than treating every new application as if it were the first.

Making the Most of a Strong Credit Profile

Good credit is a genuine asset in the alternative lending space, and business owners who understand how to use it, by comparing offers, understanding how credit affects specific products, and choosing the funding structure that best matches both their qualification profile and their actual need, tend to secure meaningfully better terms than those who accept the first approval they receive without further comparison or negotiation.

Frequently Asked Questions

Does a higher credit score always result in a lower interest rate?
Generally, a stronger credit profile supports more favorable pricing, though the specific relationship between credit score and rate varies by lender and product.

Should a business with good credit still compare multiple lenders?
Yes. Comparing offers helps ensure that a strong credit profile is actually translating into the best available terms rather than assuming the first offer received reflects the most favorable option.

Can good personal credit offset a shorter business operating history?
In many cases, yes, since a strong personal credit profile can provide additional confidence to a lender evaluating a business with a limited track record.

Is it better to use a bank loan or alternative lending with good credit?
The right choice depends on the specific tradeoff between rate and timeline for your situation, since alternative lending can offer favorable terms for good-credit borrowers while moving considerably faster than a traditional bank process.

How can a business build a stronger lending relationship over time?
Consistent, timely repayment and clear communication with a lender over multiple funding cycles tends to support increasingly favorable terms on future applications.